The Weekly Update
Week of September 7th, 2026
By Christopher T. Much, CFP®, AIF®
Stocks were mixed last week as markets continued to navigate geopolitical concerns and new signals about short-term interest rates.
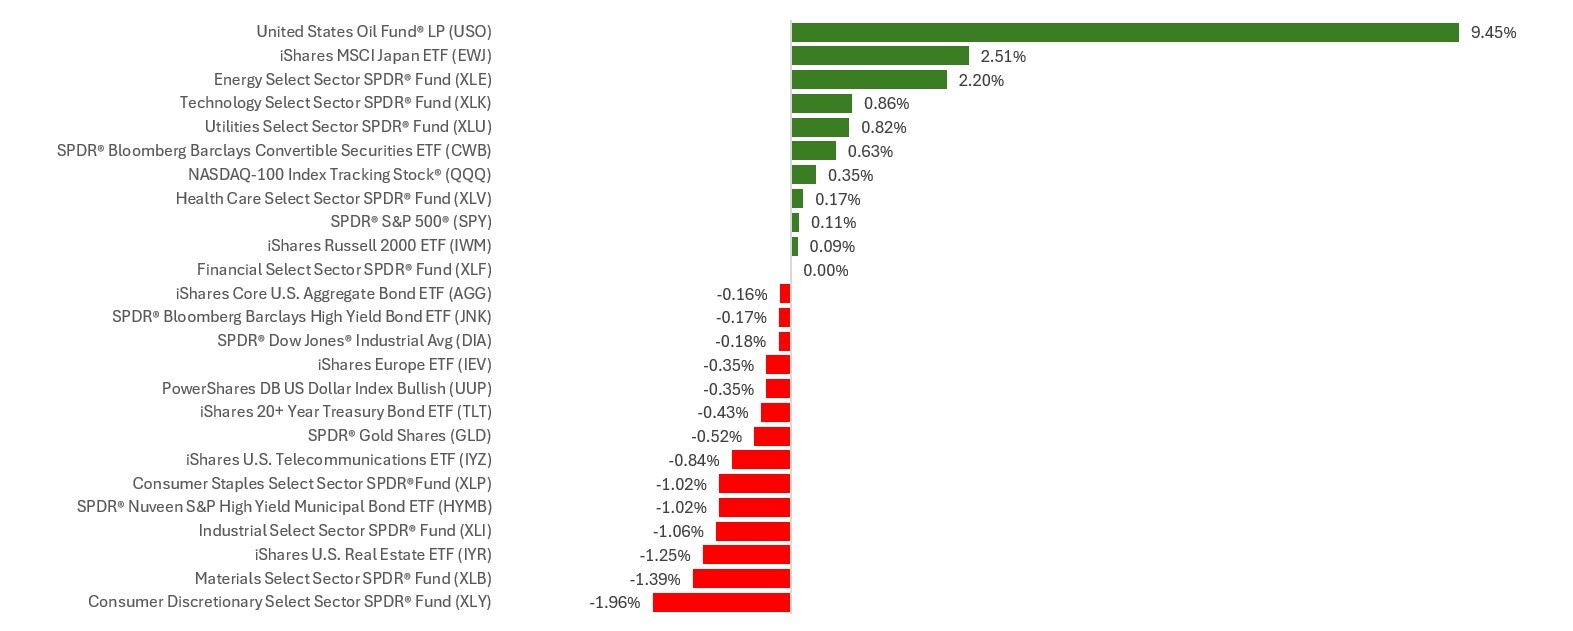
The Standard & Poor’s 500 Index edged up 0.09 percent, while the Nasdaq Composite Index rose 0.40 percent. The Dow Jones Industrial Average slipped 0.27 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, skidded 0.25 percent.
Summer’s Final Act
Stocks fell modestly, and oil prices rose at the start of the week after renewed tensions in the Middle East put investors on edge. Longer-maturity Treasury bond yields also rose, adding pressure on stocks.
Stocks remained under pressure as global bond yields rose, with traders fretting that higher oil prices would stoke broader inflation. Benchmark government bond yields for the U.S., Germany, and Japan hit 20-month, 15-year, and 30-year highs, respectively.
But midweek, stocks rebounded after Fed Governor Christopher Waller suggested that the Fed might leave interest rates unchanged at its meeting later this month. Each major average gained 1 percent or more.
Before Friday’s opening, the Labor Department’s nonfarm payrolls report showed job growth was stronger than expected in August. Stocks were under pressure all day as traders saw the jobs report as a reason that the Fed might consider adjusting rates later this month.
Jobs Update
Wednesday’s ADP National Employment Report showed private-sector hiring slowed in August, as companies added only 38,000 jobs.
That was one of the reasons why Friday’s non-farm payrolls report surprised investors. The entire U.S. economy added 162,000 jobs in August. That was triple the 53,000 job gain economists expected and the biggest jump in 5 months. The unemployment rate also remained unchanged at a historically low 4.1 percent.
This Week: Key Economic Data
Tuesday: NFIB Small Business Optimism Index. Consumer Credit.
Thursday: Weekly Jobless Claims. Producer Price Index (PPI). Monthly Wholesale Trade. Existing Home Sales.
Friday: Consumer Price Index (CPI). University of Michigan Consumer Survey. Monthly Treasury Balance.
Source: Investors Business Daily – Econoday economic calendar; September 4, 2026. The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
This Week: Companies Reporting Earnings
Tuesday: Oracle Corporation (ORCL)
Thursday: Adobe Inc. (ADBE)
Source: Zacks, September 4, 2026. Companies mentioned are for informational purposes only. It should not be considered a solicitation for the purchase or sale of the securities. Investing involves risks, and investment decisions should be based on your goals, time horizon, and risk tolerance. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost. Companies may reschedule their earnings reports without notice.